SEP IRA

SEP IRA Solutions for Self-Employed Professionals

McLane Advisors helps self-employed Texans build tax-smart retirement strategies tailored to how they actually earn. From SEP IRA setup to Solo 401(k) management, we deliver personalized guidance that reduces your tax burden and builds lasting financial security.

McLane Advisors helps self-employed Texans build tax-smart retirement strategies tailored to how they actually earn. From SEP IRA setup to Solo 401(k) management, we deliver personalized guidance that reduces your tax burden and builds lasting financial security.
Why Choose McLane Advisors

Old couple high-five while reading documents

Plans Built Around How You Earn

Self-employed income does not follow a set schedule, and your retirement plan should not assume it does. McLane Advisors designs strategies around your real cash flow, whether you are a freelancer, sole proprietor, LLC, or S Corp. We align contributions with your income patterns so you build wealth consistently without overextending your current resources or missing key savings windows.

Old couple scanning documents

Tax Advantages That Work Year-Round

Every dollar you contribute to a SEP IRA or Solo 401(k) is positioned to reduce your taxable income today while growing tax-deferred for the future. McLane Advisors integrates tax planning into every retirement strategy, helping self-employed clients across Texas keep more of what they earn and build lasting wealth at every stage of their financial life.

Business men discussing financial advice

Independent Advice, No Hidden Agenda

As independent advisors, McLane Advisors is not tied to proprietary products or internal sales targets. Every recommendation is based on what genuinely fits your business structure, income, and goals. With over 50 years of experience and 2,000+ clients served, we bring the depth and objectivity that self-employed professionals need from a trusted financial advisor.

    Retirement Plans That Fit the Way You Work

    Being self-employed means your retirement is entirely in your own hands. Without an employer matching contributions or defaulting you into a plan, every savings decision is yours to make. McLane Advisors simplifies that responsibility with clear guidance and the right plan for your situation.

    McLane Advisors Retirement Success

    What Is a SEP IRA?

    A SEP IRA (Simplified Employee Pension) is one of the most accessible retirement accounts available to self-employed individuals. Contributions are tax-deductible, accounts grow tax-deferred, and setup requires minimal paperwork, making it a strong starting point for most self-employed professionals.

    Key benefits of a SEP IRA:

    • Contributions are fully tax-deductible in the year they are made
    • High annual contribution limits based on net self-employment income
    • Easy to set up and maintain with minimal administrative requirements
    • Available to sole proprietors, LLCs, S Corps, and partnerships
    • No annual IRS filing requirement for the plan itself
    • Contribution amounts can vary year to year based on income
    McLane Advisors Financial Guidance

    The Solo 401(k) Advantage

    A Solo 401(k) is built for self-employed individuals with no employees other than a spouse. It offers higher contribution limits than a SEP IRA, Roth contribution options, and the ability to take loans from the plan. For high earners, it can significantly increase annual tax-deferred savings.

    Solo 401(k) at a glance:

    • Employee and employer contribution slots both available
    • Roth contribution option for tax-free retirement growth
    • Loan feature for added financial flexibility
    • Higher total contribution ceiling for high earners
    • Well suited for sole proprietors and single-member LLCs
    McLane Advisors Clients

    Roth Strategies for Long-Term Tax-Free Growth

    Depending on your tax bracket and goals, Roth contributions can offer significant advantages at retirement. McLane Advisors helps you evaluate whether a Roth Solo 401(k) or a backdoor Roth strategy fits your current income and long-term tax outlook.

    Flexible Planning for Freelancers and Contractors

    Freelancers and contractors face inconsistent income and irregular tax obligations. McLane Advisors builds flexible strategies with variable contribution options, so you stay on track during slower income periods without locking into rigid commitments year after year.

    Comparing Your Options

    McLane Advisors evaluates which plan structure fits your situation best. Here is how the most common options compare:

    • Best for sole proprietors, LLCs, and S Corps
    • Contribute up to 25% of net self-employment income, capped at $69,000 (2024)
    • No Roth option, no loan feature
    • Very low administrative burden
    • Best for self-employed individuals with no employees
    • Contribute up to $69,000 total through employee and employer slots (2024)
    • Roth option available, loan feature available
    • Moderate administrative requirements
    • Best for small businesses with employees
    • Employee contributions up to $16,000 (2024)
    • No Roth option, no loan feature
    • Low to moderate administrative load
    • Available to any individual with earned income
    • Contribute up to $7,000 per year (2024)
    • Roth IRA option available
    • Very low administrative burden

    See What Consistent Contributions Can Build

    This projection uses a $65,000 seed with $6,500 in annual contributions at a 7% annual return. It shows how structured, proactive planning turns regular savings into a substantial retirement fund over time.

    Year 1
    End Balance $75,075
    Annual Interest +$3,575
    Year 5
    End Balance $129,288
    Annual Interest +$8,458
    Year 10
    End Balance $221,329
    Annual Interest +$14,479
    Year 15
    End Balance $350,422
    Annual Interest +$22,925
    Year 20
    End Balance $531,482
    Annual Interest +$34,770
    McLane Advisors Team

    The People and Places Behind McLane Advisors

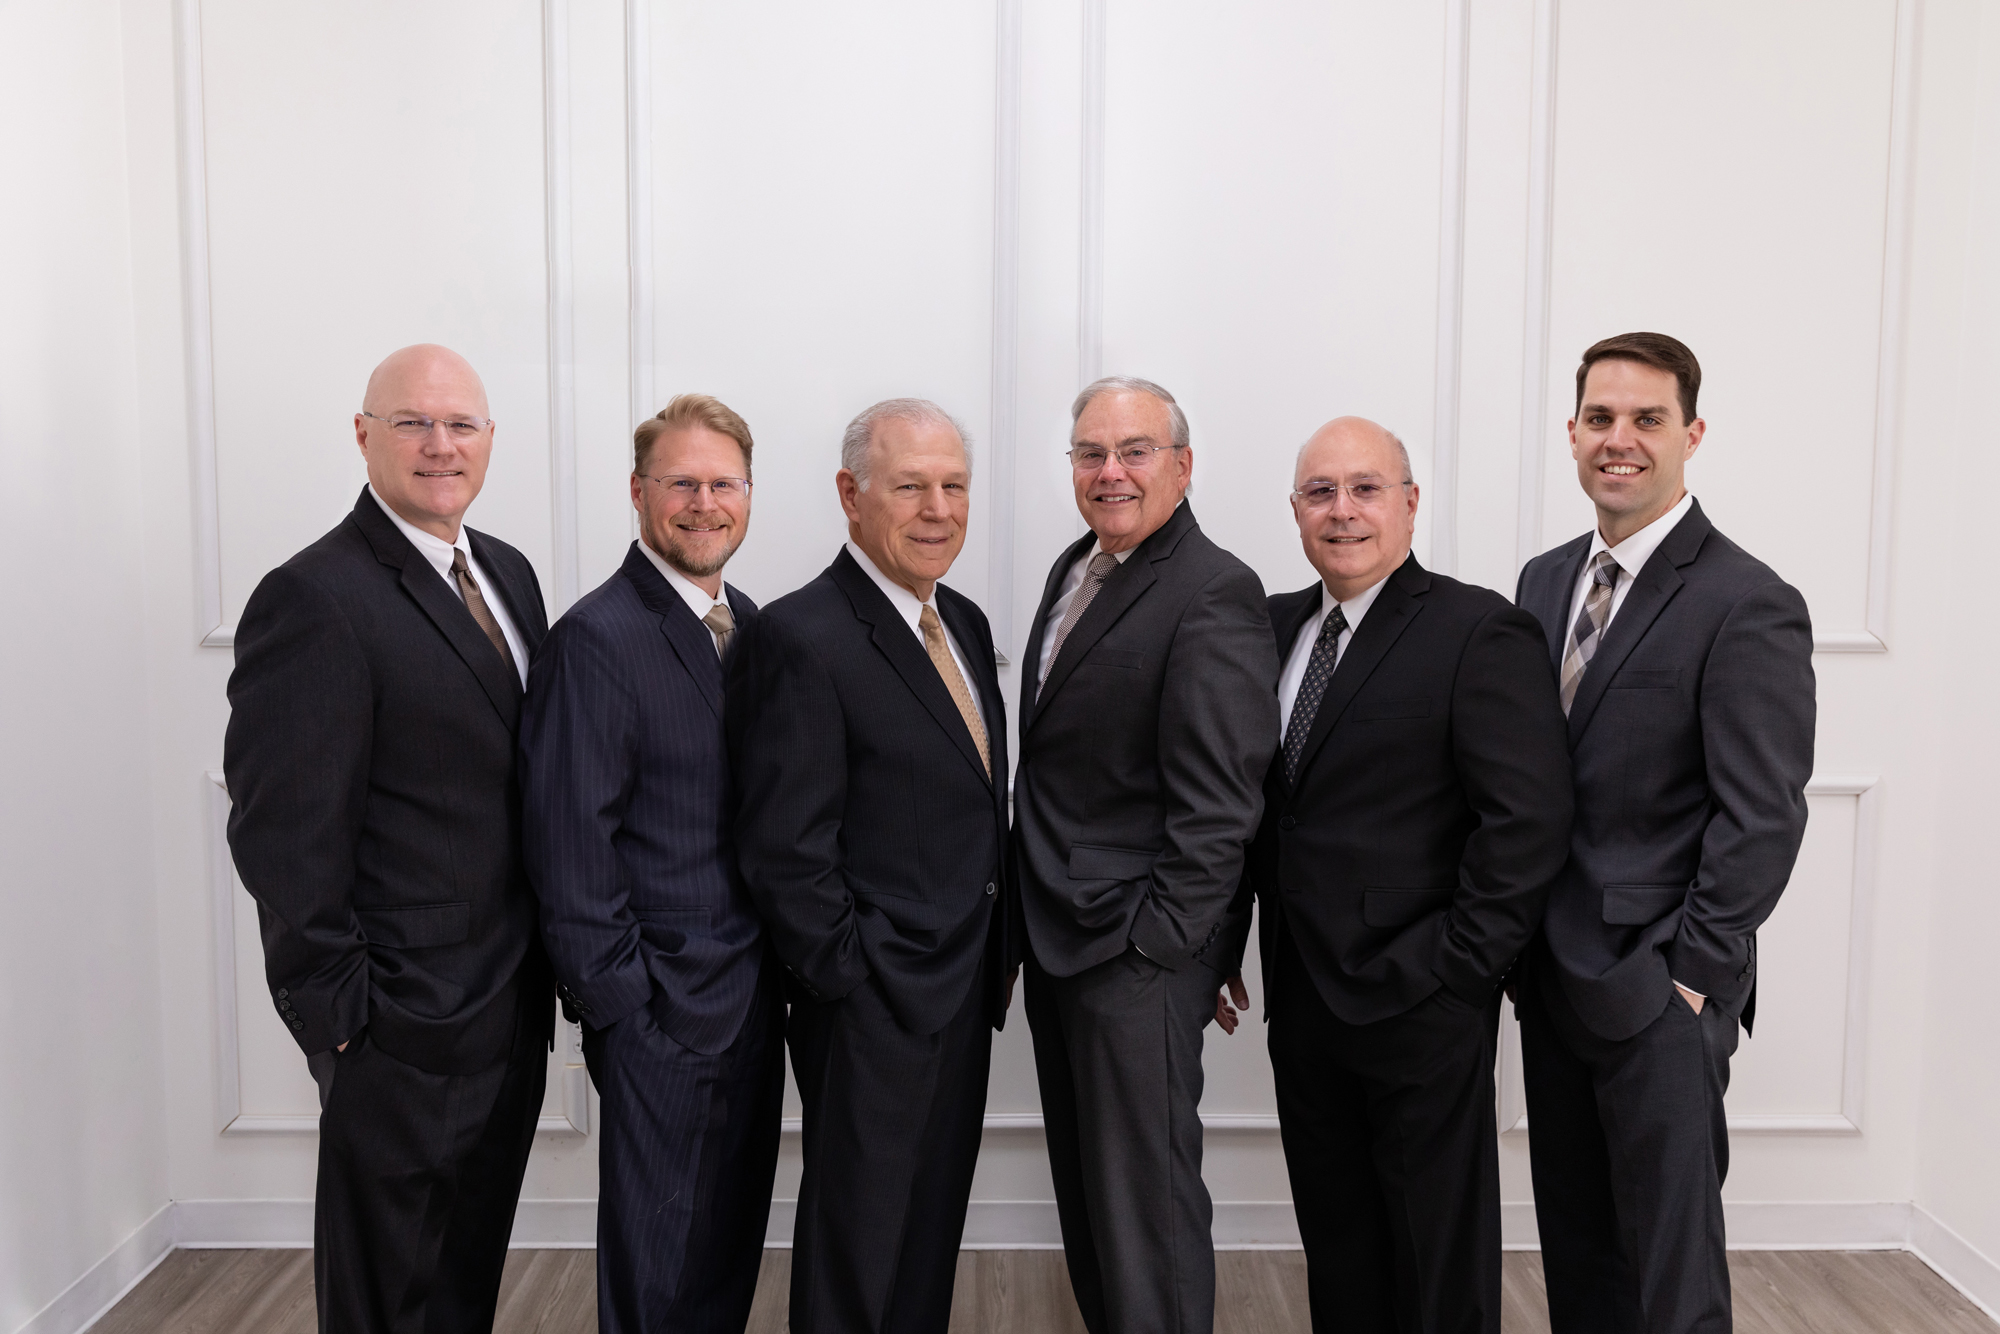
    From our offices in Montgomery and Tomball to the clients we serve across Texas and 26 other states, these photos reflect the relationships and values that have defined McLane Advisors for over 50 years.

    Trusted by Texans Across Every Walk of Life

    McLane Advisors clients come from every background and career path. Their experiences reflect decades of personalized service, sound guidance, and financial outcomes built on trust, consistency, and three generations of expertise.

    Frequently Asked Questions

    What is a SEP IRA and how does it work?

    A SEP IRA, or Simplified Employee Pension Individual Retirement Account, is a retirement savings plan that lets self-employed individuals and small business owners make tax-deductible contributions to their own retirement accounts. Contributions are made by the employer only, reduce taxable business income in the year they are made, and grow tax-deferred until withdrawn in retirement. The plan is straightforward to set up and requires no annual IRS filing for the plan itself.

    McLane Advisors helps self-employed clients open, fund, and manage a SEP IRA in a way that maximizes annual contributions without disrupting cash flow. We align your contribution amount with your net self-employment income, your tax picture for the year, and your long-term retirement goals. For many self-employed Texans, a SEP IRA is the most practical entry point into structured, high-limit retirement savings.

    Who qualifies for a SEP IRA?

    Any self-employed individual, small business owner, sole proprietor, or freelancer with earned income can open a SEP IRA. There is no minimum age requirement, and accounts can be opened and funded up until the tax filing deadline, including extensions. If you have employees, you are generally required to contribute the same percentage of compensation to eligible employee accounts as you contribute to your own, which is an important factor to consider when selecting this plan structure.

    For solo operators with no employees, the SEP IRA offers a clean, low-maintenance path to significant tax-deferred savings. McLane Advisors evaluates your business structure, income, and employee situation before recommending a SEP IRA to confirm it is the right fit. If other structures would serve you better, we say so and walk you through the alternatives clearly and honestly.

    How much can I contribute to a SEP IRA?

    SEP IRA contributions are limited to the lesser of 25% of your net self-employment income or the annual IRS cap, which was $69,000 for 2024. This is a significantly higher ceiling than a traditional or Roth IRA allows, making it a powerful tool for accelerating retirement savings during high-income years. Contribution amounts can vary year to year, which gives you the flexibility to save more when revenue is strong and contribute less when cash flow is tighter.

    McLane Advisors helps you calculate the optimal contribution for each tax year, balancing retirement savings goals against current cash flow needs and tax strategy. We factor in your total income picture, including any other retirement accounts you hold, to ensure contributions are structured for maximum efficiency. Making the most of your allowable contribution is one of the most impactful financial moves a self-employed individual can make.

    What is the difference between a SEP IRA and a Solo 401(k)?

    A SEP IRA is funded entirely by employer contributions, is easy to set up, and carries no Roth option or loan feature. A Solo 401(k) allows both employee and employer contributions, which can significantly increase total annual savings, especially at lower income levels where the SEP IRA's employer-only formula may produce a smaller deduction. Solo 401(k)s also offer a Roth contribution option and the ability to borrow from the plan, giving high earners more tools to work with.

    The right choice depends on your income level, business structure, and financial goals. High earners who want Roth flexibility or loan access often benefit from a Solo 401(k). Those who want simplicity and minimal administration often prefer a SEP IRA. McLane Advisors walks you through both options and recommends which structure, or combination, gives you the best long-term outcome for your specific situation.

    Can I have both a SEP IRA and another retirement account?

    In most cases, yes. Self-employed individuals can hold multiple retirement accounts simultaneously, though contribution limits and eligibility rules apply across all of them. You may be able to contribute to both a SEP IRA and a traditional or Roth IRA in the same year, subject to income limits. However, you generally cannot contribute to both a SEP IRA and a Solo 401(k) for the same self-employment income in the same year.

    McLane Advisors evaluates your full retirement picture before recommending any account structure. We look at what you currently hold, what you are eligible for, and how to coordinate contributions across accounts for the greatest tax efficiency and long-term growth. Our goal is always to find the combination that works hardest for you within the rules that apply to your situation.

    What are the tax benefits of a SEP IRA for self-employed professionals?

    Contributions to a SEP IRA are tax-deductible in the year they are made, directly reducing your net self-employment income and your federal tax liability. The account then grows tax-deferred, meaning no taxes are owed on gains, dividends, or interest until you take distributions in retirement. For self-employed individuals without access to an employer-sponsored plan, this combination of immediate deduction and long-term deferred growth is one of the most powerful financial tools available.

    McLane Advisors integrates SEP IRA tax planning into a broader strategy that may also include deduction timing and withdrawal sequencing in retirement. The goal is to reduce your tax burden both now and in the future, keeping more of your earnings working for you across your entire financial life. We build these strategies around your actual numbers, not general assumptions, so every recommendation reflects your specific situation.

    Is a SEP IRA right for my business structure?

    A SEP IRA works well for most self-employed structures, including sole proprietorships, single-member LLCs, multi-member LLCs, S Corps, and partnerships. The key consideration is whether you have employees, because SEP IRA rules generally require you to contribute the same percentage of compensation to eligible employee accounts as you contribute to your own. For solo operators, this is not an issue, and the SEP IRA offers a straightforward, high-limit savings vehicle with very little overhead.

    For business owners with employees, McLane Advisors evaluates whether a SEP IRA, Solo 401(k), SIMPLE IRA, or Safe Harbor 401(k) is the better fit based on your team size and benefit goals. Our small business retirement planning services cover this full range of options so you never have to navigate the decision alone. The right plan is always built from the ground up around your specific circumstances.

    How does McLane Advisors help self-employed clients choose the right plan?

    McLane Advisors starts with a conversation about how you earn, how your income varies, what your tax situation looks like, and what you want retirement to look like. From that foundation, we evaluate which account structures align with your goals: a SEP IRA for simplicity and high limits, a Solo 401(k) for Roth access, a contributory IRA for supplemental savings, or a combination. We also factor in any existing accounts and how new contributions interact with them across your full financial picture.

    The process does not stop at account setup. McLane Advisors reviews your plan regularly and adjusts contribution strategy as your income and goals change. Learn more about who we are and the values that guide every recommendation we make. Self-employed financial planning requires more flexibility than a standard employer plan provides, and we build that flexibility into every strategy we design.

    Can I roll over a SEP IRA into another retirement account?

    Yes. A SEP IRA can be rolled over into another IRA, a Solo 401(k), or most other qualified retirement plans. Rollovers are common when consolidating accounts, transitioning from self-employment to salaried work, or repositioning savings into a different investment structure. When handled correctly, a rollover is tax-free and preserves the tax-deferred status of your funds. If the distribution is not rolled over within 60 days, it may be treated as taxable income and subject to penalties.

    McLane Advisors manages rollover coordination as part of our broader retirement services. We review your existing accounts, evaluate your options, and execute the transition in a way that protects your savings. Our 401(k) and 403(b) rollover services apply the same disciplined approach to self-employed clients navigating account transitions at any stage of their career.

    How do I get started with a retirement plan at McLane Advisors?

    Getting started is straightforward. Call our Montgomery or Tomball offices during business hours, Monday through Friday from 8:30am to 2:00pm. We begin with a conversation about your business structure, income, tax situation, and retirement goals. One of the most useful first steps is a complimentary Retirement Analysis, which gives you a clear picture of where you stand today and what a stronger plan could deliver.

    From there, McLane Advisors builds a personalized strategy and walks you through every decision without jargon or pressure. Whether you are opening your first retirement account or optimizing a plan already in place, we have the expertise and independence to guide you toward the right outcome for your specific situation.

    Your Future Deserves a Plan That Works as Hard as You Do

    McLane Advisors has helped self-employed Texans build stronger financial futures for over 50 years. From SEP IRA setup to Solo 401(k) management, we deliver retirement planning that fits the way you work. With $500M+ in assets under management and a three-generation legacy of trust, your future is in expert hands.

    Book your appointment today.


    We focus on your Financial Growth

    McLane Advisors: Trusted Texas financial advisors with decades of expertise in wealth management, retirement planning, and investment strategies. Safeguard your future with personalized solutions.

    Please let us know your first name.
    Please let us know your phone number. i.e. 123-456-7890
    Please let us know your email address.
    Please write a subject for your message.
    Please let us know your message.
    McLane Advisors Investment Services

    McLane Advisors: Trusted Texas financial advisors for three generations, providing tailored strategies for financial security in Texas and 23 other states.

    Address

    Phone Number

    Todd and Chad McLane
    Phone: (888) 295-2317
    Local: (281) 357-0874
    Fax: (888) 326-6292

    Frank, Matt and York McLane
    Phone: (888) 357-0804
    Local: (281) 357-0800
    Fax: (877) 376-0280

    Jim Schulmire
    Phone: (888) 357-0804
    Local: (281) 357-0800
    Fax: (877) 376-0280

    Hours of Operation

    Monday 8:30am - 4:30pm
    Tuesday 8:30am - 4:30pm
    Wednesday 8:30am - 4:30pm
    Thursday 8:30am - 4:30pm
    Friday 8:30am - 2:00pm
    Saturday Closed
    Sunday Closed

    Securities and advisory services offered through Centaurus Financial, Inc.  Member of FINRA http://www.finra.org/index.htm and SIPC http://www.sipc.org/.  A Registered Investment Advisor. Supervisory office: 540 Fort Evans Rd NE, STE. 200 Leesburg, VA 20176, 714-456-1790. McLane Advisors and Centaurus Financial, Inc. are not affiliated. This is not an offer to sell securities, which may be done after proper delivery of a prospectus and client suitability has been reviewed and determined. Information relating to securities is intended for use by individuals residing in TX,AL,AR,AZ,CA,CO,FL,GA,IA,ID,LA,MD,MO,MS,NC,NM,OH,OK,OR,PA,SC,TN,UT,VA,WA,WI,WV.

    Securities and advisory services offered through Centaurus Financial, Inc.  Member of FINRA http://www.finra.org/index.htm and SIPC http://www.sipc.org/.  A Registered Investment Advisor. Supervisory office: 540 Fort Evans Rd NE, STE. 200 Leesburg, VA 20176, 714-456-1790. McLane Advisors and Centaurus Financial, Inc. are not affiliated. This is not an offer to sell securities, which may be done after proper delivery of a prospectus and client suitability has been reviewed and determined. Information relating to securities is intended for use by individuals residing in TX,AL,AR,AZ,CA,CO,FL,GA,IA,ID,LA,MD,
    MO,MS,NC,NM,OH,OK,OR,PA,SC,TN,
    UT,VA,WA,WI,WV.